Key takeaways
- The federal Fair Debt Collection Practices Act (FDCPA) bans abusive, deceptive and unfair debt collection practices by third-party collectors and debt buyers.
- Harassment includes threats of violence or arrest, obscene language, repeated calls intended to annoy, and publishing “deadbeat” lists. Lying about the amount owed or pretending to be a lawyer is also illegal.
- Owing money does not take away your rights. A collector can ask you to pay; it cannot bully, deceive or shame you into paying.
- Documentation is your strongest tool. A simple call log, saved voicemails and copies of letters can turn a frustrating experience into a provable claim.
- You may be able to recover actual damages, statutory damages of up to $1,000 per lawsuit, and attorney’s fees if a collector violates the FDCPA.
If you are behind on a bill, the phone ringing can start to feel like a threat. Many people assume that because they owe money, the collector holds all the power and can say or do whatever it takes to get paid.
That is not how the law works.
Since 1977, the Fair Debt Collection Practices Act has set firm limits on how debt collectors may behave. In 2021, the Consumer Financial Protection Bureau’s Regulation F added detailed rules for modern communication, including calls, emails, texts and social media. Most states have their own debt collection laws on top of the federal rules, and some of them reach even further.
This guide explains what counts as illegal debt collector harassment, the most common violations we see, and exactly how to document them so you can protect yourself.
Who the FDCPA applies to
Before you can identify a violation, you need to know whether the law covers the company contacting you.
The FDCPA applies to “debt collectors,” which generally means:
- Third-party collection agencies that collect debts owed to someone else;
- Debt buyers that purchase old accounts and then try to collect them; and
- Attorneys and law firms that regularly collect consumer debts.
It generally does not apply to the original creditor collecting its own debt under its own name, such as your credit card issuer’s internal collections department. However, many states have laws that apply to original creditors too, and federal laws against unfair and deceptive practices still apply.
The FDCPA also covers only consumer debts, meaning debts incurred primarily for personal, family or household purposes. Credit cards, medical bills, personal loans, auto loans and mortgages usually qualify. Business debts generally do not.
Not sure who is calling you? Our guide to who owns your debt and how debt buying works explains how to tell an original creditor from a collection agency or debt buyer.
What counts as harassment or abuse
The FDCPA prohibits any conduct whose natural consequence is to harass, oppress or abuse a person in connection with collecting a debt. The law lists specific examples, but the list is not exhaustive. Courts look at the overall conduct.
1. Threats of violence or harm
A collector may not threaten violence or other criminal means to harm you, your reputation or your property. This includes veiled threats like “you don’t want to find out what happens next.”
2. Obscene, profane or abusive language
Insults, slurs, swearing and language meant to humiliate you are prohibited. A collector calling you “a thief” or “a deadbeat” crosses the line.
3. Repeated or continuous calls intended to annoy
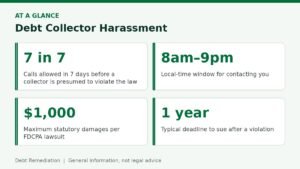
Calling over and over, or keeping the phone ringing, with intent to annoy, abuse or harass is illegal. Regulation F created a presumption about call frequency: a collector is presumed to comply if it places no more than seven calls within seven consecutive days about a particular debt, and does not call within seven days after having a telephone conversation with you about that debt. Calls above those limits are presumed to violate the law. (We cover the call rules in detail in our guide to debt collector call rules under Regulation F.)
4. Calling without identifying themselves
Except in limited situations involving locating a person, collectors must disclose who they are when they call.
5. Publishing lists of people who “refuse” to pay
Collectors may not publish your name on a list of people who allegedly refuse to pay debts, except to a consumer reporting agency.
6. Advertising your debt to coerce payment
Posting about your debt in public, on social media, or anywhere others can see it to pressure you into paying is prohibited. Regulation F specifically bars collectors from communicating with you on social media in a way visible to the public, such as posting on your wall or commenting publicly.
Deceptive and misleading practices
Harassment is not just about tone. The FDCPA also bans false, deceptive or misleading representations. These violations are often more common, and easier to prove, than outright abuse.
Watch for collectors who:
- Misstate the amount you owe, add unauthorized fees, or misrepresent the legal status of the debt;
- Pretend to be attorneys or government officials, or imply that a letter came from a court or government agency;
- Threaten arrest or jail for failing to pay an ordinary consumer debt;
- Threaten actions they cannot take or do not intend to take, such as suing on a debt they have no plans to sue on, garnishing wages without a court judgment where one is required, or seizing property they cannot seize;
- Threaten to sue on a time-barred debt (a debt past the state’s statute of limitations). Learn more in our guide to time-barred debt;
- Falsely claim that you committed a crime or engaged in fraud;
- Use a false business name or fail to disclose that they are a debt collector;
- Send documents that look like legal papers but are not; or
- Communicate false credit information, including failing to report that a debt is disputed when they know you have disputed it.
Unfair practices
The FDCPA also prohibits unfair or unconscionable means of collection, such as:
- Collecting amounts (including interest, fees or charges) that are not authorized by the agreement creating the debt or permitted by law;
- Depositing a post-dated check early or threatening to do so;
- Causing you to incur charges, such as collect calls, by concealing the purpose of the communication;
- Threatening to take your property when there is no present right to do so; and
- Contacting you by postcard, or using language or symbols on an envelope that reveal it is about debt collection.
Who collectors can and cannot talk to about your debt
Third-party disclosure is one of the most damaging forms of collection pressure. Generally, a collector may discuss your debt only with:
- You;
- Your spouse (or, in some cases, a parent if you are a minor, or a guardian, executor or administrator);
- Your attorney;
- The creditor and its attorney; and
- A consumer reporting agency.
Collectors may contact other people, such as relatives, neighbors or co-workers, only to obtain your location information. Even then, they generally may not say that you owe a debt and usually may contact the same person only once.
If a collector tells your boss, your neighbor or your family that you owe money, write down who was contacted, when and what was said. That conduct may be a violation on its own.
Where and when collectors can contact you
Under the FDCPA and Regulation F, collectors generally may not contact you:
- Before 8:00 a.m. or after 9:00 p.m. in your local time zone, unless you agree;
- At work if they know or have reason to know your employer prohibits such contact;
- Directly, if they know an attorney represents you on that debt and they can obtain the attorney’s contact information; or
- Through a specific method you have told them not to use, such as your work email.
How to document debt collector harassment
Most consumers know when something feels wrong. Proving it is another matter. The difference usually comes down to records made at the time it happened.
Step 1: Start a collection call log today
Create a log, either in a notebook or a spreadsheet, and fill it out for every contact. Record:
| Field | Example |
|---|---|
| Date and time | Oct. 14, 8:42 p.m. |
| Company name | ABC Recovery Services |
| Phone number used | (555) 010-0199 |
| Representative’s name or ID | “Mark,” ID 3321 |
| Debt referenced | Old store card, balance claimed $2,416 |
| What was said | Threatened to “send the sheriff” if not paid by Friday |
| Witnesses | Spouse heard speakerphone |
| Your response | Asked for written validation |
Our sister site, Debt Remediation Tools, also offers a free guide to dealing with debt collectors.
Step 2: Save voicemails and screenshots
Save voicemails to your phone or computer. Take screenshots of call logs showing the number and frequency of calls, along with any texts, emails or social media messages.
A note on recording calls: Massachusetts and several other states require the consent of all parties before a call is recorded. Recording a call without consent in an all-party consent state can expose you to legal liability. If you want to record, tell the collector at the start of the call that you are recording, or check your state’s rules first.
Step 3: Keep every letter and envelope
Keep collection letters, envelopes (the postmark and any markings on the outside matter), and any documents that look like court papers. Make copies and store the originals in a safe place.
Step 4: Communicate in writing whenever possible
Phone calls leave room for “he said, she said.” Written communication creates a record. Send important requests, such as a debt validation letter or a request to stop contact, by certified mail, return receipt requested, and keep copies of everything you send.
Step 5: Track the harm the conduct caused
The FDCPA allows recovery of actual damages, which can include emotional distress. Note sleepless nights, missed work, medical visits, or other ways the conduct affected your life. Documentation made at the time is far more persuasive than recollection months later.
What you can do about it
Tell the collector to stop
You have the right to tell a debt collector, in writing, to stop contacting you. Once the collector receives your letter, it generally must stop communicating with you except to confirm it is ending collection efforts or to notify you of a specific action, such as filing a lawsuit. Stopping contact does not erase the debt, and the collector may still sue. Our guide to writing a cease-and-desist letter explains when this is a good idea and when it can backfire.
File complaints
You can submit complaints to:
- The Consumer Financial Protection Bureau (consumerfinance.gov/complaint);
- The Federal Trade Commission (ReportFraud.ftc.gov); and
- Your state attorney general. In Massachusetts, the Attorney General’s Office accepts consumer complaints, and the Massachusetts Division of Banks licenses debt collectors operating in the state.
Complaints create a regulatory record, and companies often respond to them.
Talk to a consumer protection attorney
If a collector has violated the FDCPA, you may be able to sue for:
- Actual damages, such as financial losses and emotional distress;
- Statutory damages of up to $1,000 per lawsuit, even if you cannot prove actual losses; and
- Reasonable attorney’s fees and court costs.
Because the law allows fee shifting, many consumer attorneys handle FDCPA cases with no upfront cost to the client. Lawsuits generally must be filed within one year of the violation, so do not wait.
If you have already been sued on the debt, FDCPA violations may be relevant to your defense or a counterclaim. Read our guide on how to answer a debt collection lawsuit and speak with an attorney before your response deadline.
Common myths about debt collector harassment
“If I owe the money, they can do whatever they want.” False. The FDCPA protects consumers whether or not the debt is valid.
“They can have me arrested.” Not for an ordinary unpaid consumer debt. Threatening arrest for nonpayment is a classic deceptive practice. (Ignoring a court order is a different matter, which is one more reason never to ignore court papers.)
“Collectors can call my family and tell them I owe money.” Generally false. Third-party contact is tightly restricted.
“If I tell them to stop calling, the debt goes away.” False. A cease-communication request stops most contact but does not cancel the debt.
Know your rights, then know your numbers
Collection pressure can push people into payments they cannot sustain. Read our free guide to dealing with debt collectors on Debt Remediation Tools, then use the Debt-to-Income Calculator to see how much of your income your debts already take.
Frequently asked questions
The law does not set a per-day limit. Instead, Regulation F presumes a violation when a collector places more than seven calls within seven days about a particular debt, or calls within seven days after a phone conversation with you about that debt. Calling repeatedly with intent to annoy or harass is illegal regardless of the count.
Yes, collectors may use texts and emails, but they must give you a simple way to opt out of those channels, and they must follow rules about privacy and timing.
Generally no, when the creditor collects its own debt in its own name. State laws and other federal consumer protection laws may still apply.
Write down the date, time, name and exact words used. Save any voicemail. Then consider filing complaints with the CFPB and your state attorney general and consulting a consumer protection attorney.
No. Filing a complaint with a regulator does not affect your credit report.
The bottom line
Debt collection is legal. Harassment, deception and unfair tactics are not. The most powerful thing you can do is keep careful records from the very first contact: dates, times, names, words and documents. Those records protect you whether you decide to dispute the debt, negotiate a resolution or pursue a claim.
If collection activity is overwhelming you, Debt Remediation can help you organize your records and prepare written requests that put the burden of proof back where it belongs. Contact us to learn how our process works.
This article is for general educational purposes and is not legal advice. Debt Remediation is a service of Foxboro Consulting Group, Inc. and is not a law firm. Laws vary by state and change over time; consult a licensed attorney about your specific situation.